
Uganda’s National Social Security Fund reported the highest revenue and the largest asset base in its history for the year to June: Shs32.8tn ($8.9bn) under management, up 26 per cent, and Shs6.5tn in revenue, up 85 per cent on the year before. Most of that revenue increase, however, was never collected as cash.
Only Shs3.9tn of the total was realised income: interest, dividends and rent the Fund actually received. Interest income rose 21 per cent to Shs3.5tn and dividends climbed 55 per cent to Shs369bn, while rental income slipped 4 per cent to Shs16bn. The remaining Shs2.6tn reflects unrealised gains from marking the Fund’s bond and equity holdings to market, a paper sum that grew nearly sevenfold on the year before and exists only on the balance sheet until those assets are sold. It is realised income, not the headline figure, that funds what members are eventually paid.
The Fund’s numbers, presented to journalists in Kampala on Wednesday, also show contributions from members rising 13 per cent to Shs2.4tn and benefits paid out climbing 17 per cent to Shs1.5tn, spread across just over 46,000 recipients.
Equities now make up 18.4 per cent of NSSF’s assets, up from 13.3 per cent a year earlier, as regional stock markets rallied; the Uganda Securities Exchange’s local index rose from roughly 1,287.6 points to 2,064.0 over the period. Fixed income, still three-quarters of the Fund’s holdings, gained too, as falling bond yields across Kenya, Tanzania and Uganda lifted the value of existing positions. A weaker shilling added to the effect: managing director Patrick Ayota explained that the Fund’s regional holdings are worth more once converted back into shillings when the currency depreciates.
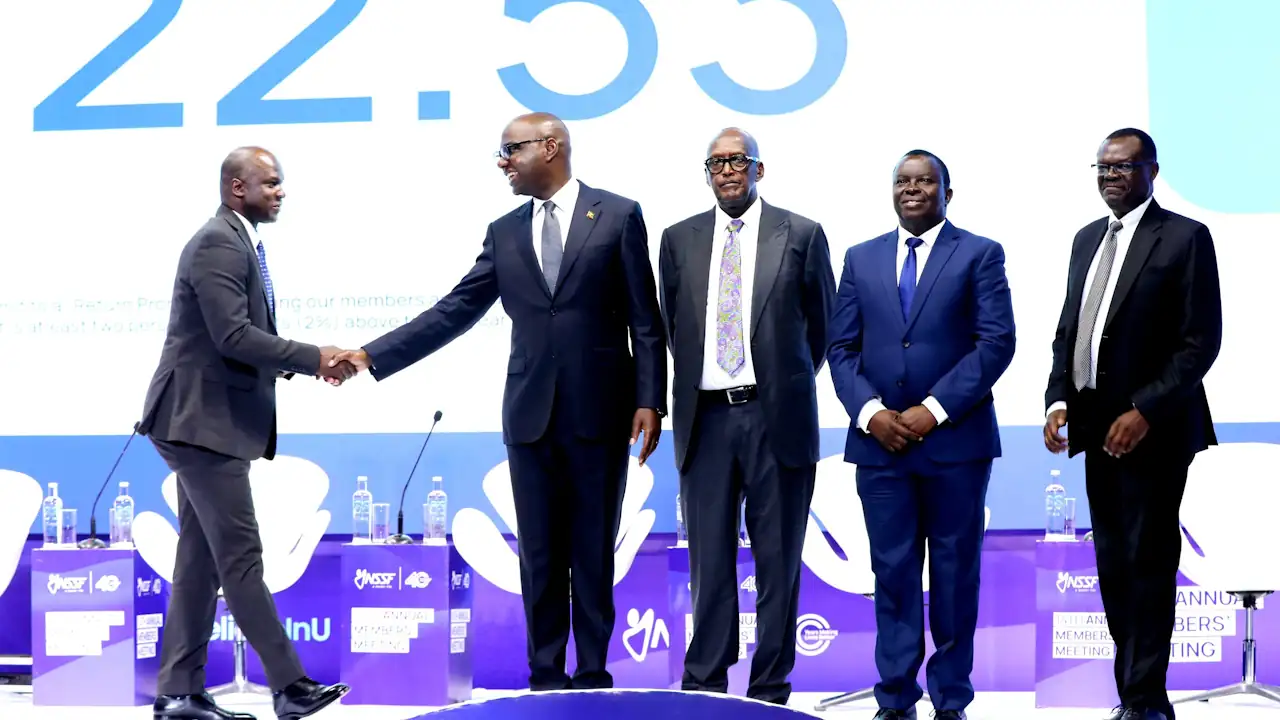
None of this affects what members actually earn this year, which is fixed by realised income and declared separately. That rate will be announced on 24 September, at NSSF’s 14th Annual Members Meeting, by Henry Musasizi, in his first such declaration since taking over the finance ministry in May from Matia Kasaija, who held the post for eleven years. NSSF has committed to a “return promise” of paying at least two percentage points above the ten-year average rate of inflation, now at 3.7 per cent, and the rate has risen every year since 2023: 10 per cent for 2022/23, 11.5 per cent for 2023/24, and 13.5 per cent last year.
Bank of Uganda data show the 91-day Treasury bill, against which much of NSSF’s bond book is priced, averaging 11.2 per cent over the year to June 2026, down from 12 per cent at the close of the previous financial year, and slipping to 10.4 per cent by August. This year’s declared rate is backed by income already earned and is not at risk. Future returns are another matter: if yields keep falling, a fixed income book that size will struggle to repeat this year’s pace of realised income growth, let alone this year’s paper gains.
Administration costs fell to 0.8 per cent of assets from 0.9 per cent, and the average time to pay a benefit dropped to 4.5 days, from nearly two weeks in 2022.
Growth in the Fund’s voluntary savings product has outpaced the mandatory scheme, and unlike this year’s headline number, it is growth in actual contributions. Smartlife Flexi has collected Shs180bn from more than 135,000 savers since its launch in November 2024, up from Shs27bn and roughly 40,000 savers a year ago. It is open to informal-sector workers, a group with no employer to deduct and remit contributions on their behalf.
NSSF covers about 3.4 million members, only 850,000 of them active, drawn almost entirely from formal private-sector employment. The International Labour Organisation puts contributory pension coverage in sub-Saharan Africa at about 6.3 per cent of the working-age population, against 9.6 per cent for Africa as a whole.
Uganda’s placing in the 2025 Absa Africa Financial Markets Index sets the two halves of this against each other. The country climbed to third of 29 economies, behind only South Africa and Mauritius. Pension fund development is its weakest category at 26 out of 100. That score rose seven points in a year when 19 countries fell back on the measure, but the gain came from the ratio of pension assets to domestically listed securities rather than from the size of the pension pool, where Uganda scores 17. The index’s authors recommend micro-pensions and simpler digital contributions as the route to the informal sector — close to a description of what Smartlife Flexi is attempting.
The Fund’s growth is real, yet a smaller share of it is money members can already count than the headline number implies. NSSF has operated as Uganda’s only mandatory scheme since cabinet killed a bill to open the sector to competing providers in 2018; whether more Ugandans come to hold a stake in the fund depends on reaching workers the compulsory scheme doesn’t cover, not on how this year’s gains happened to be booked.